By Jim Lineweaver, CFP®, AIF®
Perhaps there’s a hospital that cared for someone you love, a school that opened doors for you, or a local organization you’ve supported for years. You’d like to do more, but you also want to know that you and your spouse will have enough for the years ahead.
A charitable gift annuity can help you balance those goals by providing fixed lifetime payments in exchange for a permanent gift. It may also offer tax benefits. Before committing, though, you’ll want to understand what you’re giving up, how the payments work, and whether the charity can meet its promise.
What is a charitable gift annuity?
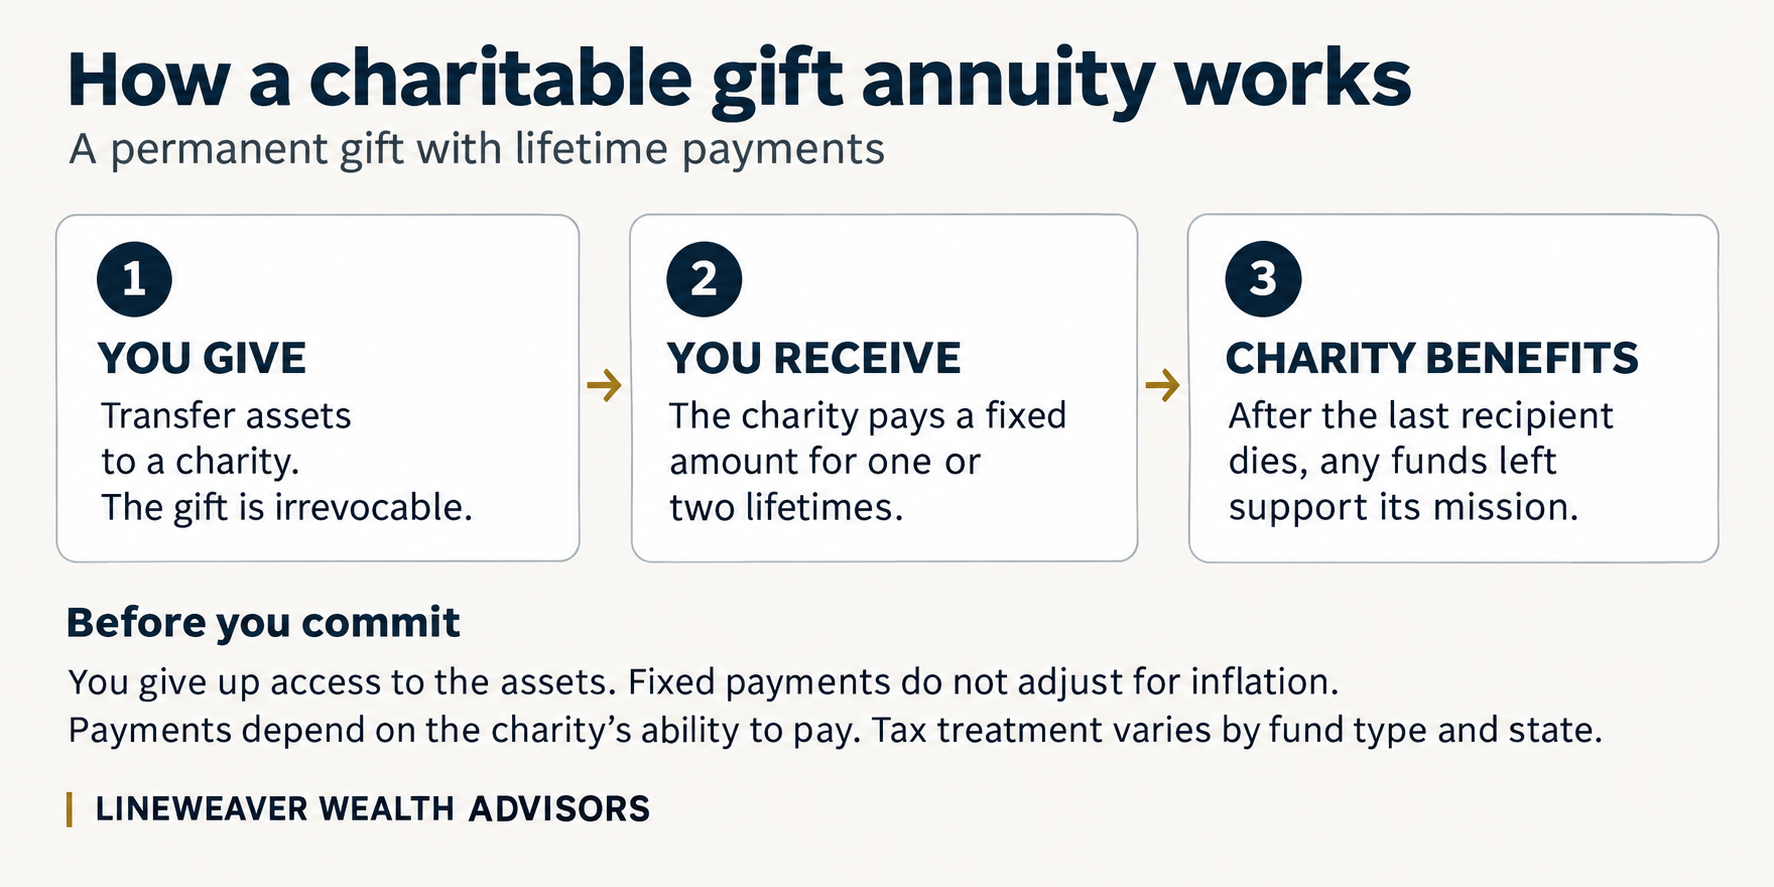
A charitable gift annuity is a contract between you and a qualified charity. You transfer assets, and the charity agrees to make fixed payments to one or two people for life. After the last recipient dies, any remaining value supports the charity’s work.
You can think of it as making a lasting commitment to a cause while keeping a stream of payments for yourself. The distinction matters: you keep the right to those payments, but you no longer own the assets or have access to them if your plans change.
How do charitable gift annuities work?
Start with the organization you want to support. If it offers gift annuities, its planned-giving team can explain which assets it accepts and prepare an illustration for you. Cash and marketable securities are common choices; other property requires the charity’s approval and may add complexity.
A charitable gift annuity example
Suppose you fund a charitable gift annuity with $100,000 in cash at an assumed 6% annual payout. That would provide $6,000 each year, or $1,500 each quarter under a quarterly payment agreement.
The 6% rate is hypothetical, so you would need a quote based on your circumstances. Ask the charity to show both the potential deduction and the expected taxes on your payments. That gives you a more useful picture of what the gift would mean for your household budget.
How payout rates work
Many charities follow the American Council on Gift Annuities’ suggested maximum rates. Your age, whether payments cover one or two lives, and when they begin influence the rate. Older recipients generally receive higher rates, while covering two lives generally lowers the rate compared with one life of the same age.
It’s tempting to compare that percentage with a bond yield. However, annuity payments may include a return of principal, and you’ve permanently transferred the underlying assets. The payout rate alone cannot tell you whether this is a good financial choice.
Charitable gift annuity pros and cons
What you may appreciate about the arrangement
For someone who already plans to make a meaningful gift, the ability to receive payments along the way can make the decision feel more manageable. You can establish your charitable commitment now while continuing to receive income for everyday expenses or other retirement priorities.
Those fixed payments also make budgeting easier. You know the amount the charity has agreed to pay, without having to decide which investments to sell each month to produce that portion of your income.
Depending on how you fund the gift, you may also receive a partial tax deduction or favorable treatment of some payments. It’s worth understanding those benefits, while keeping your reason for giving at the center of the decision.
What deserves a closer look
The biggest commitment is the gift itself: once you transfer the assets, you cannot take them back. Before deciding on an amount, leave room for possibilities such as long-term care, helping an adult child, or a move you haven’t yet planned.
Inflation deserves attention, too. A payment that feels useful today will buy less as prices rise. Your remaining savings and other income need to help cover that difference.
You also depend on the charity’s ability to pay. Even when an organization has personal meaning for you, review its finances and annuity program with the same care you would give another long-term commitment.
Finally, talk through what the gift means for your family. You may feel strongly about supporting the charity and still want to provide for your spouse or children. Considering those wishes together can help you choose an amount you’re comfortable giving permanently.
A charitable gift annuity can affect your retirement income, taxes, and long-term financial goals. Learn how coordinated wealth planning can help you balance charitable giving with your family’s financial needs.
How does the funding source affect taxes?
Cash and appreciated securities
A charitable gift annuity funded with cash may provide a partial tax deduction. The calculation accounts for the value of the payments you receive, so you cannot deduct the full gift. Payments generally include taxable income and, for a period, a tax-free return of part of your investment in the contract.
With appreciated securities, payments may also include capital gains. The IRS’s gift annuity reporting instructions distinguish taxable income, capital gains, and nontaxable amounts. Giving stock does not automatically eliminate all capital gains tax.
If you itemize, 2026 charitable deduction rules allow deductions only for eligible contributions above a floor of 0.5% of adjusted gross income. Other limits may apply. Have your tax advisor review the proposed gift alongside your income and other giving before relying on a projected tax benefit.
Using an IRA to fund your gift
If you are at least 70½, a special rule allows qualifying IRA transfers to fund a charitable gift annuity. For 2026, the IRS sets the one-time transfer limit at $55,000. This transfer counts toward your $111,000 annual qualified charitable distribution, or QCD, limit.
Under IRS rules, the annuity must be funded entirely with QCDs and begin fixed payments of at least 5% annually within one year of funding. Only you, your spouse, or both can receive the income. You can use this election in only one tax year during your lifetime.
A qualifying transfer can count toward your required minimum distribution and avoids inclusion in income, but it gives you no separate charitable deduction. Later payments from the IRA-funded annuity are ordinary income. An outright QCD supports the charity without providing payments back to you.
Is a charitable gift annuity right for you?
This arrangement may suit you if you have a clear charitable goal, want fixed payments, and can comfortably set aside the donated assets. If you’re still unsure what retirement will cost or expect substantial family expenses, keeping access to those funds may matter more.
You also have other charitable giving strategies to consider. An outright gift is simpler when you don’t need payments. A charitable remainder trust offers different payment options and can support broader charitable goals, with added costs and ongoing management.
Before signing, ask:
- What assets will the charity accept, and what payment terms will it offer?
- How strong are its finances and the reserves supporting its promises?
- Will enough remain outside the gift for your spending, family needs, and unexpected costs?
- What would you actually receive after taxes?
Make room for giving in your retirement plan
You don’t have to settle every detail before starting a conversation. Begin with the organization you want to help, what you hope your gift will accomplish, and what you need to feel comfortable about retirement.
Align Your Charitable Giving with Your Financial Goals
Charitable gift annuities involve important decisions about retirement income, taxes, and your legacy. Our team can help you evaluate how charitable giving fits into your broader financial picture and long-term goals.
Frequently Asked Questions About Charitable Gift Annuities
No. A charitable gift annuity is irrevocable. Your contract gives you the right to payments, but you cannot withdraw the donated assets later.
Financial distress could interrupt payments. The ACGA explains that the charity’s unencumbered assets back its obligation, although that backing does not remove the risk of default.
Yes. A two-life agreement can provide for both spouses. Review how much the surviving spouse would receive and how that income would fit their needs.
A gift annuity is a contract with a charity. A charitable remainder trust holds assets separately and pays beneficiaries before the remainder passes to charity. Its structure determines whether payments stay fixed or change.